Homeowner Tips
Should a Contractor See Your Insurance Estimate?
Understand why a roofing contractor may request an insurance estimate, what it contains, and questions to ask before sharing claim documents.
Talk about your roofBy Joel ScullyPublished Last updated 4 min read
One of the most common questions homeowners ask after a roof claim is:
“Should I share my insurance estimate with my roofer?”
The short answer:
Usually yes — if you trust the contractor.
But there are definitely pros and cons homeowners should understand before sharing their adjuster report or Scope of Loss.
At Texas Professional Roofing, we believe homeowners should understand how the process actually works so they can make informed decisions.
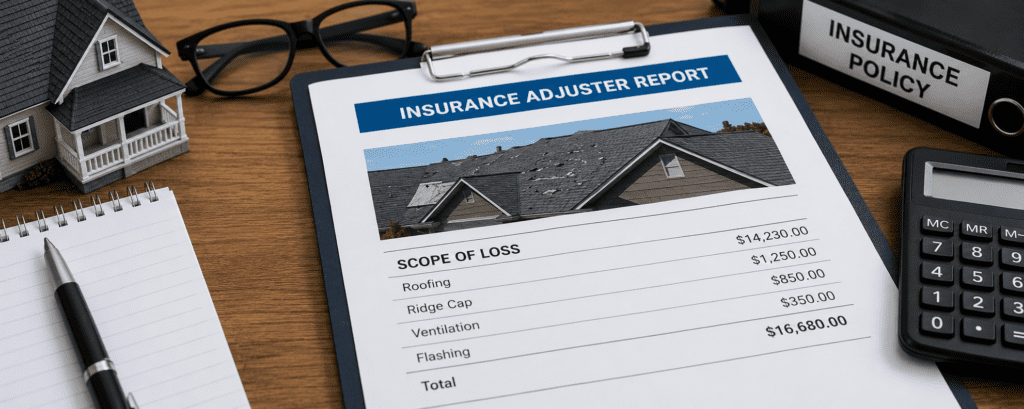
What Is an Adjuster Report or Scope of Loss?
After a roof inspection, the insurance company typically creates a document called:
- Scope of Loss
- Adjuster Report
- Insurance Estimate
This document outlines:
- approved repairs
- measurements
- material quantities
- labor pricing
- code items
- depreciation
- deductible
- total claim value
It essentially becomes the insurance company’s version of the project scope.
The Pros of Sharing Your Insurance Estimate
1. Helps Identify Missing Items
One of the biggest benefits:
experienced roofers can spot omissions quickly.
Items to compare against the actual roof and proposed work include:
- drip edge
- starter shingles
- ridge cap
- ventilation upgrades
- flashing replacement
- steep charges
- high charges
- code requirements
- decking replacement
- valley metal
- chimney flashing
Reviewing the report allows the contractor to:
- Compare physical roof conditions with listed construction quantities.
- Document observed omissions with photographs and measurements.
- Provide a construction estimate for the policyholder and insurer to review.
The insurer determines whether any additional work is covered. TDI roofing and insurance guidance explains why the roofer’s construction role is separate from acting as a public adjuster.
2. Prevents Pricing Confusion
A roofer can prepare an independent construction estimate from the roof inspection. The insurer’s estimate provides separate context about its assessed scope.
The contractor may not know:
- what was approved
- what was denied
- what the carrier expects
- whether code upgrades were included
This can create unnecessary back-and-forth later.
Sharing the report helps align:
- scope
- expectations
- project planning
Organize Construction Documentation
A contractor can help document the physical work by:
- Recording measurements and observed conditions.
- Providing photographs and construction quantities.
- Explaining the proposed materials and repair work.
Sharing an estimate does not guarantee a faster claim decision.
Keep the Construction Price and Insurance Settlement Separate
Request an itemized contract price for the agreed work. An insurer’s estimate is not a universal market tariff, and the roofing contract need not equal the claim total. Ask how hidden conditions and optional upgrades are priced and approved.
The Cons of Sharing Your Insurance Estimate
1. Some Contractors Only Chase the Insurance Maximum
This is probably the biggest homeowner concern.
Some contractors see the insurance payout and immediately attempt to:
spend every dollar available
—even when unnecessary.
That may lead to:
- inflated upgrades
- unnecessary add-ons
- higher-pressure sales tactics
Not every contractor operates this way, but homeowners should be aware of it.
2. It Becomes Harder to Compare Contractors
Once contractors see the insurance number, many proposals suddenly become:
“insurance proceeds”
instead of detailed project pricing.
That makes apples-to-apples comparisons more difficult for homeowners.
3. Bad Contractors May Focus More on the Claim Than the Roof
Homeowners should be cautious of contractors who seem more interested in:
- claim totals
- supplement volume
- insurance payouts
than:
- installation quality
- ventilation
- workmanship
- project management
The focus should always remain:
protecting the home correctly.
4. Some Contractors May Pressure Homeowners
Occasionally contractors use the insurance paperwork to create pressure:
- “Insurance already approved it.”
- “You have to sign now.”
- “You can’t shop around.”
That is NOT true.
Homeowners are still allowed to:
- ask questions
- compare contractors
- review scopes
- choose who they trust
The Real Truth: The Contractor Matters More Than the Estimate
The key issue is not:
whether you share the report
The real issue is:
who you are sharing it with.
A trustworthy roofing contractor uses the estimate to:
- protect the homeowner
- identify missing items
- streamline the process
- improve communication
- ensure proper installation
A poor contractor may simply use it as a sales tool.
Best Practice for Homeowners
A smart approach is usually:
1. Choose the Contractor First
Select someone based on:
- reputation
- communication
- experience
- warranties
- professionalism
- insurance knowledge
—not simply price.
2. Then Share the Insurance Estimate
Share only relevant information after deciding who needs it and why. Consider redacting unrelated personal or financial details, and ask how documents will be retained.
3. Ask Questions
Good questions include:
- What items are missing?
- Are code upgrades included?
- Will supplements likely be needed?
- Are flashings being replaced?
- Is ventilation being addressed?
- Will decking replacement be extra?
Homeowners Should Remember
The insurance company’s estimate is:
often a starting point — not the final scope.
Additional construction documentation may be needed if the inspection identifies items such as:
- steep slopes
- multiple elevations
- complex flashing
- ventilation issues
- code upgrades
- decking damage
An experienced contractor can help properly document those items.
Final Thoughts
In most situations:
sharing your adjuster report with a trusted roofing contractor is beneficial.
It usually:
- Clarifies the insurer’s assessed construction scope.
- Helps identify differences that need explanation.
- Supports discussion of quantities and materials without deciding coverage.
But homeowners should still:
- vet contractors carefully
- avoid high-pressure sales tactics
- focus on quality and trust
- understand the scope themselves
Because at the end of the day:
the quality of the contractor matters far more than the paperwork itself.
What would you like to do next?
Start with a number, book a look at the roof, or just ask.